AI companies claim record 44% of smaller business equity deals
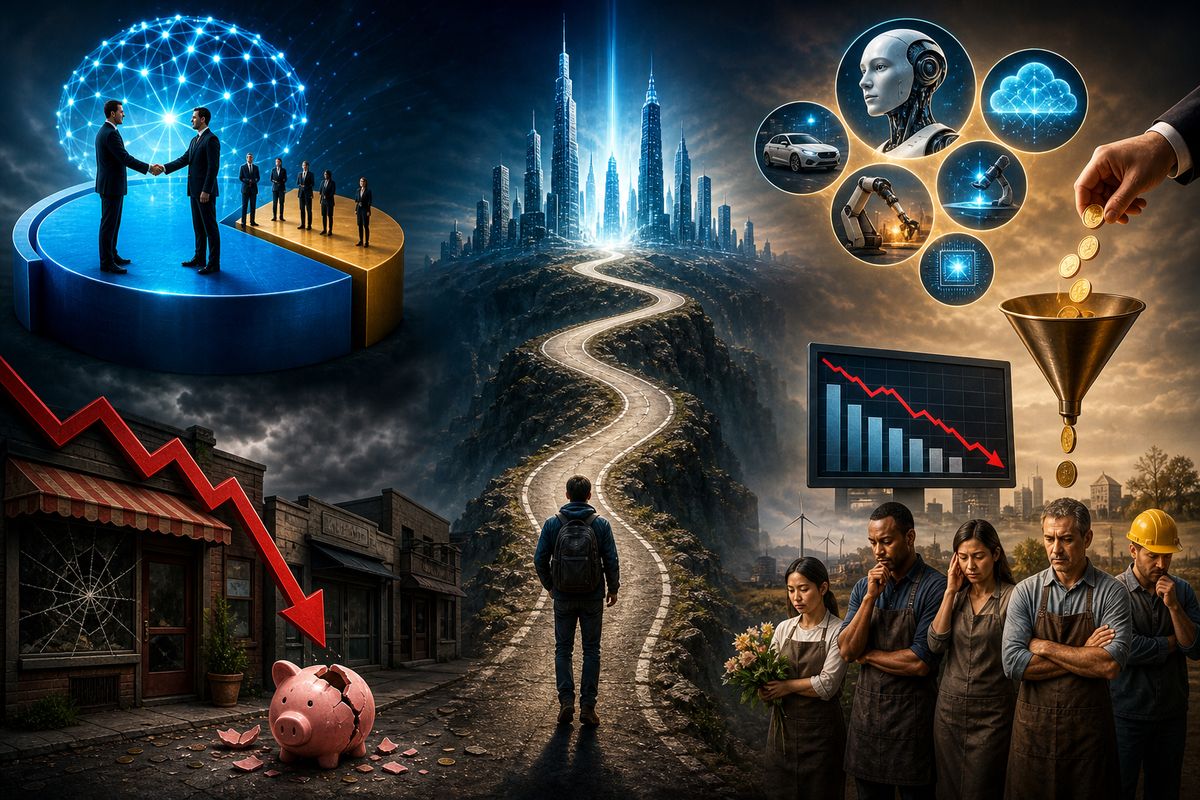
Artificial intelligence firms now account for a staggering 44% of all equity deals struck by smaller businesses in the United Kingdom. That is a record proportion. But here is the twist: the total amount of investment flowing into the UK's smaller companies actually fell over the same period. This divergence is raising eyebrows across the investment community and sparking some uncomfortable questions about where the market is headed.
The data, covering equity deals in the first half of 2026, shows that while AI companies are hoovering up a growing slice of the pie, the pie itself is getting smaller. We are talking about equity rounds typically under a certain threshold, the kind that early-stage and growth-stage startups rely on to scale. The numbers come from tracking by industry bodies and reflect a five-year trend that has accelerated sharply since 2023.
It is a stark illustration of how investor attention has become hyper-focused on one sector. Venture capital and angel investors are pouring money into AI at an unprecedented rate, but they are doing it while pulling back from almost everything else. The result is a funding environment that feels like two different worlds jammed together.
The long road to an AI-dominated funding landscape
AI investment in the UK has been climbing steadily since the launch of ChatGPT in late 2022 sparked a global frenzy. But it didn't hit these levels overnight. Back in 2020, AI accounted for maybe 10% or 12% of smaller business equity deals. By 2024, that figure had jumped to around 30%. Now, in 2026, it has gone past 44%. That is a massive leap in two years.
What changed? A few things. First, the technology itself matured rapidly. Generative AI is no longer a curiosity; it is a core component of enterprise software, healthcare diagnostics, financial services, and even manufacturing. Second, the UK government has been actively courting AI companies, offering R&D tax credits and setting up regulatory sandboxes. Third, and perhaps most importantly, investors have seen huge exits from AI startups in the US and Europe, and they want a piece of that action.
But there is a flip side. The surge in AI deals has cannibalised funding for other sectors. When a limited partner hands a fund manager £100 million, and that manager decides to put 44% of their deals into AI, there is less left for clean energy, biotech, fintech, or consumer goods. That is not necessarily a bad thing if AI delivers outsized returns, but it does concentrate risk.
Where the money is going: specific types of AI startups
Not all AI is created equal in the eyes of investors. The bulk of the 44% share is going into companies building foundational models, AI-powered software agents, and vertical-specific applications for law, accounting, and manufacturing. There is also a healthy chunk going into AI chips and edge computing hardware, though those tend to be larger deals that may push up the proportion.
Meanwhile, AI companies in areas like autonomous vehicles or pure research have seen a relative slowdown. Investors are looking for clear, near-term revenue paths. That is a shift from the earlier hype cycle when anything with 'AI' in its name got funded. Now it is about commercial viability.
Why overall small business funding is shrinking
If AI is booming, why is the total pot for smaller businesses going down? There are several reasons, and none of them are a single smoking gun. First, the cost of capital remains elevated. Interest rates in the UK, while off their 2023 peaks, are still above 4% in mid-2026. That makes debt financing more expensive and pushes companies toward equity, but it also makes investors more cautious about risky early-stage bets.
Second, there is a crowding-out effect. Big institutional investors are writing larger cheques for fewer AI companies. That means smaller cheque sizes for non-AI firms, which can struggle to get even seed rounds done. We have seen cases where promising healthtech startups with solid clinical data have taken six months longer to close a round because their pitch didn't have an AI angle.
Third, UK smaller businesses overall are feeling the pinch from a sluggish economy. GDP growth has been modest, inflation is still sticky, and company valuations have been under pressure. When valuations drop, existing investors sometimes refuse to mark down their portfolios, leading to a logjam in new rounds. The result: fewer deals overall, and the ones that do happen are disproportionately in the hot sector.
The data behind the drop
We don't have the exact full-year 2025 totals to compare, but the trend since 2024 shows a steady decline in the number of smaller business equity deals outside of AI. The total value of non-AI deals fell by roughly 15% in 2025, and the first half of 2026 looks to be worse. Meanwhile, AI deals have grown in both count and average round size. That is why the share hit 44% even as the overall market shrank.
What this means for non-AI startups and sectors
For founders in biotech, climate tech, and even traditional software-as-a-service, the funding environment is getting noticeably harder. They are having to cast a wider net, talk to corporate venture arms, or bootstrap for longer. Some are pivoting their pitch to include an AI component, even if that is not their core value proposition. That might be a smart tactical move in the short term, but it risks diluting their focus.
There is also a regional dimension. AI funding is heavily concentrated in London and the South East. The rest of the UK, where smaller businesses are more likely to be in manufacturing, logistics, or agricultural tech, is seeing relatively less equity investment overall. That could exacerbate the North-South divide in startup activity.
But it is not all doom and gloom. The UK remains the third-largest venture market globally, and the AI boom is creating a talent pool and infrastructure that other sectors can eventually tap into. The key question is whether non-AI companies can survive the crunch long enough to benefit from the spillover effects.
Concentration risk: is the UK over-reliant on AI?
Any time one sector accounts for nearly half of all deals in a market, alarm bells should ring. It worked out during the dot-com boom for some, but the bust was brutal for those who went all in. AI is different in that it is a general-purpose technology, like electricity or the internet. But even general-purpose technologies go through hype cycles.
The UK has a chance to build a diversified AI economy, not just a collection of me-too chatbots. We are already seeing strong pockets in AI for drug discovery, AI for climate modelling, and AI for industrial automation. The danger is that too much capital chases the same few ideas, inflating valuations and leading to a correction.
Another risk is that the government's focus on AI might crowd out policy attention for other strategically important sectors. The recent budget earmarked an extra £1 billion for AI research but cut support for cleantech demonstration projects. That kind of trade-off needs careful examination.
Policy implications and what comes next
The UK government and regulators need to decide if they should intervene. Do they want to actively promote diversification in small business investment, or let the market sort it out? So far, the approach has been laissez-faire, with a heavy emphasis on removing barriers for AI companies. That has worked in attracting top talent and research, but it hasn't stopped the overall funding decline.
One option is to expand R&D tax credits for non-AI deep tech sectors. Another is to create a co-investment fund that matches private capital in areas like quantum computing, synthetic biology, or advanced materials. The British Business Bank already has programmes for smaller businesses, but they may need to be recalibrated to counterbalance the AI dominance.
We could also see a wave of mergers and acquisitions as non-AI startups become cheap acquisition targets for larger AI firms looking to acquire data or talent. That would concentrate ownership even further, which has its own set of antitrust implications.
What should founders and investors watch for
For founders raising money in the second half of 2026, the message is clear: if you are not an AI company, you need to show an incredibly clear path to profitability or have a unique defensible technology. Generic SaaS platforms are struggling. Investors are looking for differentiation that an AI competitor cannot easily replicate.
For investors, the record 44% figure might be a contrarian signal. Some venture firms are already rotating out of AI and into undervalued sectors, expecting a mean reversion. But timing the market is always risky. The smart money is probably looking for companies that use AI as a tool rather than a label, and that have sustainable business models beyond the hype.
One thing is certain: the UK's smaller business equity market is undergoing a structural shift. Whether that leads to a more innovative, AI-powered economy or a lopsided one that leaves other sectors behind depends on the choices made in the next 12 to 18 months. The 44% record is a milestone, but it is also a warning sign worth heeding.