Why this comparison matters for TUI river cruise passenger complaints in 2026
Anyone searching for tui river cruise passenger complaints is usually trying to answer a very practical question: what is the smartest route to get money back, and how do you avoid making things worse? Because once a holiday has gone wrong, the next steps can either protect a claim or quietly kill it. And in the TUI River Cruises case, the details matter, a lot.
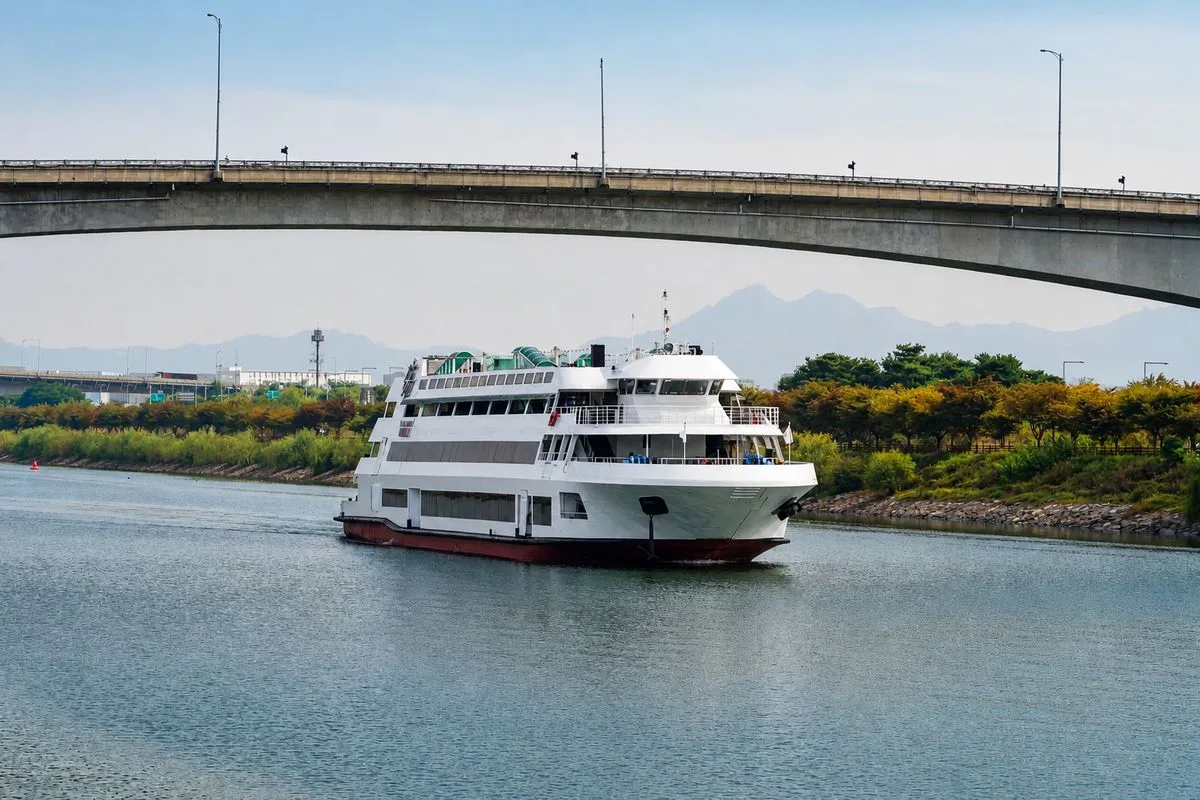
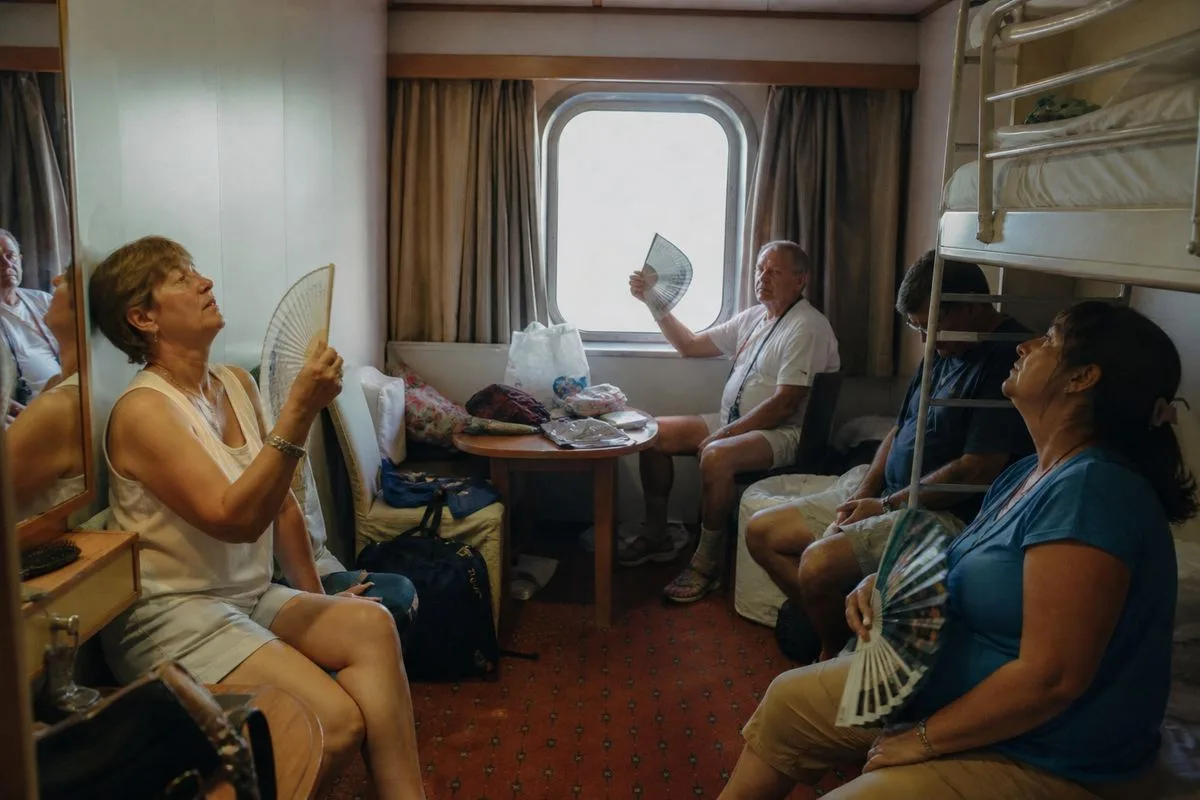
The immediate trigger is a run of complaints reported this summer about TUI River Cruises sailings on the Skyla and Isla. Passengers describe broken or absent air conditioning, sewage smells, and toilets that do not function across multiple sailings. Some say they were told in writing that air conditioning was working, then found out on arrival from a holiday representative that it was not. TUI apologises where trips “fell short of the standards we aim to deliver” and says it is investing in upgrades across its European river cruise fleet this winter.
So the decision point for affected passengers is not just “complain to TUI”. It is a comparison between three realistic paths: accepting TUI’s settlement (cash or vouchers), pursuing travel insurance for curtailment or other cover, and using consumer law under the Package Travel and Linked Travel Arrangements Regulations 2018. They can overlap, but they can also clash. That is where people get caught out.
What is happening: the specific complaints, the offers, and the time pressure
According to reporting referenced by the insurance trade press, the complaints span multiple sailings on Skyla and Isla during summer 2026. The headline issues are not minor niggles. Air conditioning failures on a European river cruise can turn cabins into ovens, and sewage smells or non functioning toilets are, frankly, the kind of thing that makes a holiday feel unliveable. These are “core service” problems, not optional extras.
The compensation examples that emerge are also telling. One couple reportedly pays nearly £4,000 for a seven day trip in June 2026 and is offered £300, with 72 hours to decide. Another passenger accepts £140 per person after air conditioning fails. The pattern here is not just the amounts, it is the structure: quick decisions, partial refunds, and the implied message that taking something now might be easier than fighting later.
And then there is the alleged miscommunication. A passenger is reportedly told by TUI customer services in writing that the air conditioning is working, only to be told on arrival by a holiday representative that it is not. If that is accurate, it shifts the story from “technical failure” to “expectation management” and potentially “misleading information”, which matters for how complaints are framed and what remedies might apply.
TUI’s response, as reported, is twofold: an apology where standards are not met, and a commitment to winter upgrades across the European river cruise fleet. That is a classic operational response, fix the hardware, reduce repeat incidents. But for passengers already affected, the question is compensation and redress now, not next season.
TUI river cruise passenger complaints: choosing between operator refunds and travel insurance
This is the heart of the comparison. When a cruise goes wrong, passengers often assume travel insurance is the obvious backstop. But the insurance angle is more conditional than people realise. The key point flagged by the insurance industry coverage is that curtailment cover typically pays only for losses not already recovered from the tour operator. In plain English, if TUI pays something, insurance may only consider the remaining gap.
The Financial Ombudsman Service position, as summarised in the reporting, is that most policies do not cover losses that are recoverable from another source. That matters because a package holiday organiser has primary liability for “lack of conformity” in the services delivered. So insurers often treat the tour operator as first in line. Insurance becomes secondary, and sometimes only after the operator route is exhausted.
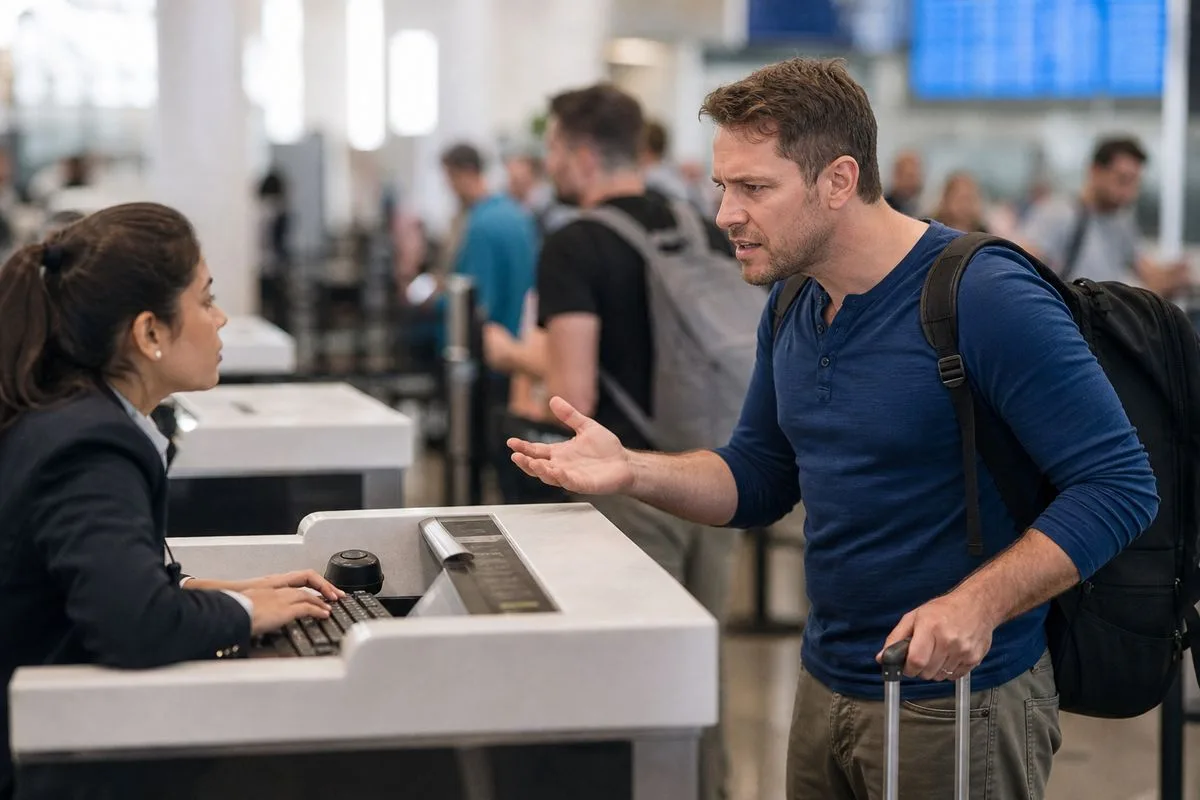
There is also a timing and settlement trap. If a passenger accepts TUI’s cash settlement, the claimable amount through insurance may reduce to the difference between what TUI paid and the actual loss. That is not necessarily bad, but it can be if the settlement is low and the policy has exclusions or strict definitions of what counts as a covered loss. And if the passenger accepts vouchers, the complication can be bigger. Consumer guidance cited in the reporting warns that taking vouchers “may also affect other ways to claim”, including travel insurance. The logic is simple: a voucher can be treated as compensation already provided, or as acceptance of a final settlement, depending on wording.
So the comparison is not “refund or insurance”, it is “refund structure and wording” versus “policy wording and evidence”. The smartest move is often to slow down, document everything, and understand what is being signed away. Easy to say, harder to do when someone is dangling money with a 72 hour deadline.
How the law stacks up: Package Travel Regulations vs insurance policy wording
For UK travellers, the Package Travel and Linked Travel Arrangements Regulations 2018 sit in the background of this story like a quiet superpower. They make organisers liable for any “lack of conformity” in the services delivered, and they require price reductions and compensation for resulting damage. In other words, if the package is not what was sold, the organiser is on the hook. That organiser, in these cases, is TUI.
That legal route is different in character from an insurance claim. Insurance is a contract with definitions, exclusions, and a claims process designed around risk pooling. Package travel rights are consumer protection, designed to make the organiser fix problems and compensate when they cannot. If the core facilities on a ship do not work, that is not a random misfortune, it is a service failure. The regulations are built for that.
But there is a catch, and it is the same catch that trips people up everywhere: final settlement language. The insurance industry commentary is blunt that insurance may respond to residual loss, but only before a final settlement is accepted. Once a passenger signs something that says “full and final settlement”, it can become much harder to argue for more, whether from the operator or from an insurer who now sees the matter as resolved.
In practical terms, passengers weighing these options need to compare not just outcomes, but leverage. Package travel rights can be strong, but they may require persistence and clear evidence of “lack of conformity”. Insurance can be faster in some scenarios, but only if the policy actually covers the event and the operator has not already compensated in a way that blocks further recovery.
Side by side comparison: TUI settlement vs travel insurance vs Package Travel claim
To make the trade offs clearer, here is a structured comparison. It is not legal advice, and it cannot replace reading the exact policy or settlement terms. But it reflects the key issues raised by the reporting and the way these disputes typically play out.
| Dimension | TUI cash or voucher settlement | Travel insurance claim (curtailment or related cover) | Package Travel Regulations 2018 route |
|---|---|---|---|
| What it is | Operator offered compensation for service shortfall | Claim under an insurance contract, often secondary to operator liability | Consumer law remedy for “lack of conformity” in a package holiday |
| Speed | Can be quick, sometimes with short acceptance windows (example: 72 hours) | Varies, can be slow if insurer asks for evidence of operator recovery first | Often slower, may involve escalation and detailed correspondence |
| Risk of limiting other claims | Medium to high, especially if labelled “full and final” or if vouchers are accepted | Medium, insurers may reduce payout by amounts recovered from TUI | Medium, but generally targets the organiser directly rather than duplicating recovery |
| What you must prove | That the holiday fell short, plus negotiation leverage | That the loss fits policy definitions and is not recoverable elsewhere | That services did not conform to the contract, and damage resulted |
| Best for | People who want quick closure and are satisfied with the amount | People with strong cover who have a clear residual loss after TUI’s response | People who believe the holiday was materially not as sold and want full redress |
What stands out is that none of these options is automatically “the best”. The best choice depends on the scale of the loss, the strength of the evidence, and how the settlement is framed. If the offer is small and the problems are severe, rushing into acceptance can be a false economy.
Also, the story is not happening in a vacuum. Travel insurance is under pressure. Complaints to the Financial Ombudsman Service about travel cover rise 58% year on year in Q3 2025, and travel insurance becomes the third most complained about product line in UK general insurance, with more than one in three cases upheld against insurers. That does not mean insurers are always wrong, but it does mean passengers should expect friction and should prepare their claim properly.
Pros and cons: quick settlement vs fighting for full redress
People dealing with tui river cruise passenger complaints tend to split into two camps. Some want a fast, clean outcome, even if it is not perfect. Others feel, with some justification, that a holiday costing thousands should not be written off with a token gesture. Both reactions are understandable. The trick is matching the approach to the situation.
TUI settlement (cash or vouchers)
- Pros: Potentially fast resolution; money in hand; less paperwork than a formal claim; avoids insurer disputes.
- Cons: Can be low compared with total holiday cost (example: nearly £4,000 trip offered £300); short decision windows; may reduce or complicate insurance claims; vouchers may limit other routes.
Travel insurance claim
- Pros: Can cover residual losses after operator compensation; provides a structured dispute route; ombudsman escalation exists if insurer rejects unfairly.
- Cons: Curtailment cover often excludes losses recoverable from the operator; payouts can be reduced by what TUI already paid; evidence burden is high; the market is contentious, with rising complaints and a significant uphold rate.
Package Travel Regulations 2018 route
- Pros: Targets the organiser’s legal liability for lack of conformity; aligns with service failure scenarios like faulty facilities; can support price reduction and compensation.
- Cons: Can be slow; requires persistence and documentation; outcomes depend on facts and how the contract is defined; passengers still need to avoid signing away rights in a settlement.
One more nuance that often gets missed: a partial settlement is not always a bad idea, but the wording is everything. If the settlement is explicitly partial and does not waive further rights, it may simply reduce the remaining claim. If it is “full and final”, it can close doors. That is why the acceptance window pressure matters, it pushes people to decide before they have read the small print or checked their policy.
And yes, it is boring admin. But boring admin is what gets people paid.
What this means for the river cruise and insurance industries
River cruising sells itself on comfort and predictability. It is not the open ocean, it is not supposed to be rugged. So when basic onboard systems fail, the reputational hit can be outsized. The Skyla and Isla complaints land at a time when travellers are already more vocal, more review driven, and less patient with “operational issues” as an excuse.
TUI’s promise of winter upgrades suggests the company sees this as a fleet reliability problem, not a one off. That is significant. It implies capital spending, scheduling downtime, and a recognition that the product needs to meet modern expectations, especially around climate control. European summers are not getting cooler, and older vessels, or vessels with underperforming systems, will struggle. If air conditioning is marketed or implied, it has to work. Fair enough.
On the insurance side, the story highlights a growing tension: consumers expect insurance to step in when holidays go wrong, but insurers increasingly point to operator liability first. That is not new, but it is becoming more visible. The numbers underline the pressure. ABI member insurers settle more than 500,000 travel claims in 2024, worth £472 million, described as one of the highest payout totals on record. Yet curtailment accounts for only 4% of all claims in that period, which hints at how narrow some of these “holiday ruined” scenarios can be in insurance terms.
There is also a trust issue. Consumer advocates raise concerns about travel insurance acceptance rates, with some providers paying out on as few as 65% of travel claims submitted, according to the reporting. That does not prove wrongdoing, claims can be invalid. But it does mean passengers should not assume a smooth ride. Documentation, timelines, and clarity about what has already been recovered from TUI become central to success.
How to handle TUI river cruise passenger complaints without weakening a claim
This is where practical steps matter more than outrage. Passengers who experience failures like broken air conditioning, sewage smells, or non functioning toilets should treat the situation like a dispute that may need evidence. That means keeping written records, taking photos where appropriate, and logging dates and times. It also means keeping copies of any messages from TUI, especially if there is a contradiction between what customer services says and what staff on the ground admit.
Before accepting any offer, passengers should read the settlement terms slowly. If it is cash, check whether it is described as “full and final”. If it is vouchers, be even more cautious, because guidance cited in the reporting warns vouchers may affect other ways to claim, including insurance. And if the offer comes with a 72 hour deadline, that is a signal to pause, not a reason to rush. A deadline is a negotiating tactic as much as it is an administrative one.
For those considering insurance, the key is to understand that curtailment cover only pays for losses not already recovered from the tour operator, as highlighted in the reporting. So the claim narrative should be clear about what TUI has paid, what remains unpaid, and why the remaining loss fits the policy. If the passenger believes they were materially misled, the Package Travel Regulations route may be relevant, because it goes to lack of conformity and organiser liability, rather than trying to squeeze a service failure into an insurance definition.
None of this guarantees success. But it changes the odds. It turns a complaint into a case.
The Verdict: the best route depends on the size of the gap, and the paperwork
For passengers caught up in tui river cruise passenger complaints on Skyla or Isla in summer 2026, the most sensible comparison based conclusion is this: take TUI’s settlement only if it is genuinely acceptable and does not close down other options. If the offer is small relative to the holiday cost, like the reported example of nearly £4,000 for a seven day trip with a £300 offer, it is hard to see why a passenger would rush to accept without checking what rights they are signing away.
Travel insurance is not a magic wand, but it can be useful for the residual loss, the gap between what TUI pays and what the passenger can reasonably argue they lost. The catch is that insurance is picky. It cares about recoverability, definitions, and evidence. Given the wider context, with FOS travel insurance complaints up 58% year on year in Q3 2025 and more than one in three cases upheld, passengers should expect insurers to scrutinise claims and should prepare accordingly.
And for travellers who believe the holiday was not delivered as sold, especially where there is alleged written assurance that air conditioning was working followed by an admission on arrival that it was not, the Package Travel Regulations 2018 route looks like the most structurally aligned option. It targets the organiser’s responsibility for lack of conformity. It may take longer. It may be a slog. But it is designed for exactly this kind of dispute, where the product itself fails, not where a random event disrupts travel.
The uncomfortable truth is that there is no single “best” answer. But there is a best process: document, slow down, and do not sign away rights for the sake of a quick payout. In 2026, that is what separates passengers who feel fobbed off from passengers who actually get made whole.
Closing thoughts: a small decision now can shape the outcome later
TUI’s winter upgrade promise suggests the company wants to draw a line under the operational side of this. Good. River cruising should be comfortable, not a test of endurance. But the compensation and claims side will run longer, because it is about individual losses, individual paperwork, and individual choices made under pressure.
For anyone dealing with tui river cruise passenger complaints right now, the biggest risk is not the broken air conditioning itself. It is accepting a settlement in a rush, then discovering that the insurance route is limited, or that a voucher counts as compensation already received, or that “full and final” really does mean full and final. Not exactly groundbreaking, but it is where people get stung.
The smart play is to treat the aftermath like a comparison exercise, not an emotional one. Operator settlement versus insurance versus legal rights. What does each require, what does each restrict, and what does each realistically pay? Answer those questions, and the next step becomes a lot clearer.