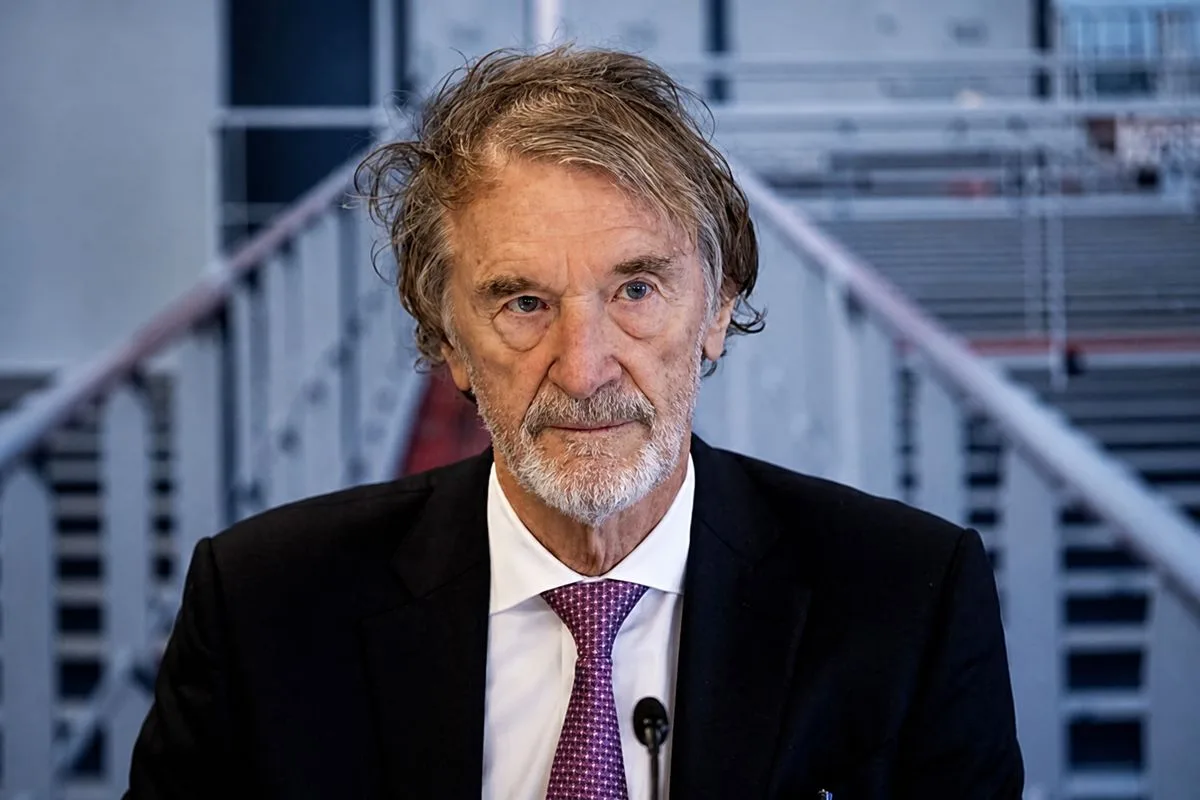
Sir Jim Ratcliffe Lausanne Sport sale, what is happening and why it matters
The sir jim ratcliffe lausanne sport sale story is not just another bit of football finance gossip. It is a clear signal that INEOS, the group fronted by Ratcliffe and now deeply embedded at Manchester United, is reshaping its sports portfolio in real time. According to reporting published on 26 October 2026, Lausanne Sport has been put up for sale roughly nine years after INEOS bought the Swiss Super League club.
And the timing is not subtle. The news lands less than a day after Manchester United lose 3 to 0 at home to Bournemouth, leaving United 16th in the Premier League in the early part of the 2026 to 2027 season. Lausanne Sport, meanwhile, is also struggling, sitting bottom of the 12 team Swiss top flight after 10 games, with one league win. When multiple clubs in the same ownership group are wobbling at once, owners tend to simplify. Or they get burned trying to juggle it all.
For anyone searching this keyword, the core question is straightforward: is Ratcliffe really selling Lausanne Sport, how, and what does it mean for INEOS, Manchester United, and multi club ownership more broadly? The available source material points to a formal sales process already underway, with advisers engaged and documents circulating. That is the difference between a rumour and a move.
Inside the reported sale process, Project Striker and the advisers involved
The reporting says Alvarez & Marsal, a global consultancy firm, is tasked with selling Lausanne Sport. That is a notable detail because it suggests a structured process rather than a casual feeler. A sales prospectus has reportedly been sent to potential investors, and it is said to be titled Project Striker. Those are the kinds of code names used when owners want a clean, discreet transaction, particularly when the seller is simultaneously dealing with intense scrutiny elsewhere.
The prospectus reportedly describes Lausanne Sport as “an established top flight contender”. That language is doing a lot of work. Lausanne Sport has been relegated three times since 2014 and promoted most recently three years ago. It is not exactly a stable “contender” in the way a buyer might understand that word in England, Germany, or Spain. But in sales documents, the pitch is rarely about what the club is today. It is about what the club could be with the right capital, recruitment, and infrastructure.
There is also a second strand to this story that matters. INEOS has already been exploring a sale of OGC Nice since May last year, using New York based investment bank Lazard to run that process. Put the two together and it looks less like a one off and more like a deliberate retreat from owning multiple football clubs outright.
It is worth being precise about what is known and what is not. The source material does not provide a valuation, a shortlist of bidders, or a target timeline. It also does not confirm whether INEOS is seeking a full sale, a majority sale, or a partial stake disposal. But the involvement of advisers and the circulation of a prospectus strongly implies INEOS wants an exit, not a minor reshuffle.
Why the sir jim ratcliffe lausanne sport sale is happening now
Start with performance, because football has a way of turning strategic plans into urgent ones. Lausanne Sport finishes fifth in the 2023 to 2024 Swiss Super League season, then drops to ninth last term, and is now bottom after 10 games with only one win. That is a sharp downward curve in a short period. A club in trouble is harder to sell at a premium, but it can also push an owner to sell before further deterioration makes the asset even less attractive.
Then there is the Manchester United factor. Ratcliffe, through INEOS, buys a minority stake from the Glazer family in February 2024 and takes on responsibility for football operations. By late October 2026, United is in a crisis mood again, and the reporting notes intense speculation about the future of head coach Michael Carrick. It also states Carrick is United’s third boss in just over two and a half years of INEOS being delegated responsibility for management of football operations. That is a brutal statistic, and it speaks to churn, pressure, and the sense that the project is not settling.
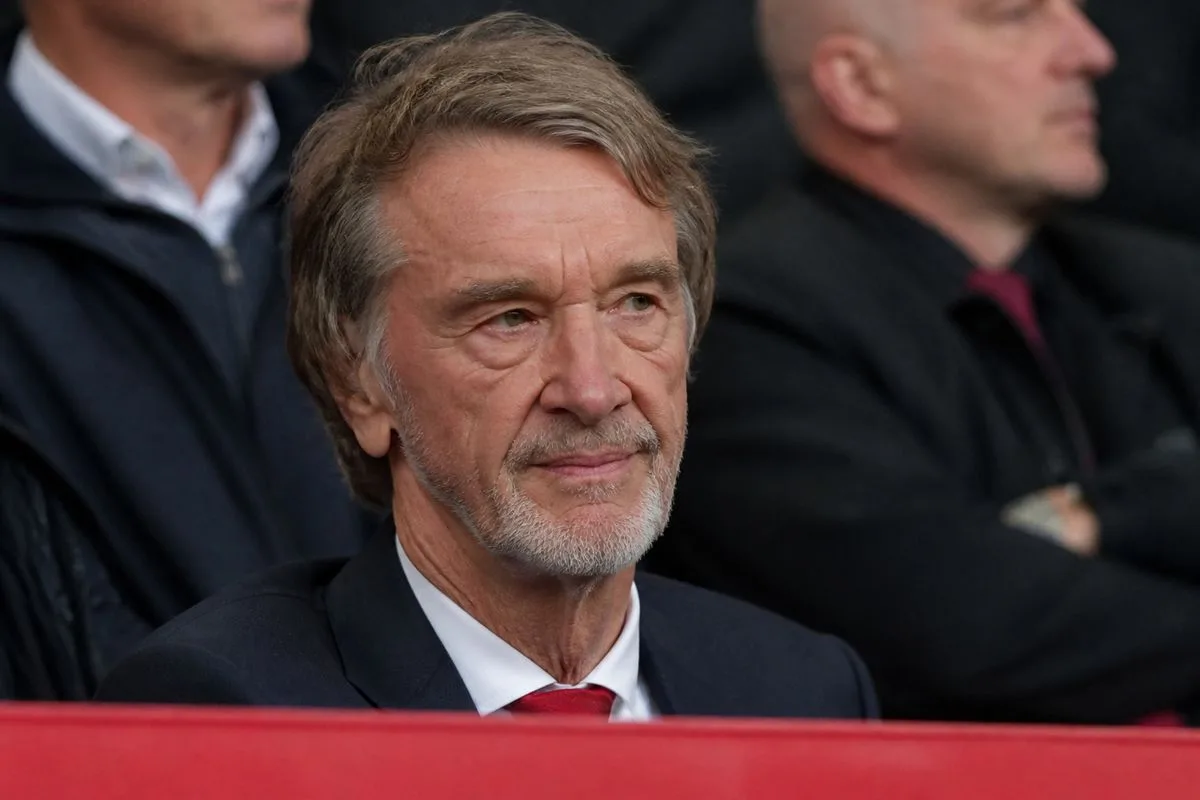
In that environment, owning and overseeing additional clubs becomes less of a “nice to have” and more of a distraction. Multi club ownership can work when the flagship is stable and the satellite clubs are aligned. But when the flagship is wobbling, every other asset starts to look like something that should either feed the flagship more efficiently or be sold to free up attention and cash.
Finally, there is the corporate context. Ratcliffe outlines INEOS priorities for 2026 in a quote included in the source material: “We need to get our businesses in the best shape that we can, which means low cost; we have to reduce our cap x; we have to spend every pound carefully and manage our businesses well.” That is not football talk. That is a cost discipline message. If INEOS is tightening capital expenditure and focusing on core priorities, trimming a portfolio of sports assets fits the mood.
INEOS, Ratcliffe and the multi club model, how Lausanne Sport fits in
Ratcliffe’s sports footprint is broad, and that is part of why this sale lands with a thud. INEOS owns stakes in multiple clubs, most notably Manchester United via its minority position, and it owns OGC Nice outright. Lausanne Sport is another outright owned club, and it has a particular historical link: the club is based in the same city as INEOS headquarters were between 2010 and 2016, before the headquarters move to Knightsbridge. That Lausanne connection has always made the ownership feel slightly more personal than a purely opportunistic investment.
But football ownership is rarely sentimental for long. The multi club model is usually justified on three pillars: player development pathways, scouting and data sharing, and commercial leverage. In theory, a group can sign a young player, develop him in a lower pressure league, then move him up the chain. In practice, it is messy. Different leagues have different rules, different fan expectations, and different competitive realities. And when results dip, the “synergy” pitch starts to sound like corporate jargon.
Lausanne Sport’s recent record, as described in the source material, undercuts the idea of a smooth development platform. Relegations and promotions create instability, and instability makes it harder to plan recruitment and coaching. It also makes it harder to sell the club as a predictable asset. A buyer might still see upside, but they will price in risk.
There is also the reputational angle. Multi club ownership is increasingly scrutinised across Europe, especially when clubs in the same network could, in theory, meet in European competition. The source material does not mention any regulatory pressure in this case, so it would be wrong to claim that is the driver. Still, in the wider industry, owners are learning that running several clubs at once is not just a spreadsheet exercise. It is politics, governance, and constant stakeholder management.
What Lausanne Sport’s on pitch slide says about the asset INEOS is selling
Any serious look at the sir jim ratcliffe lausanne sport sale has to grapple with what exactly is being sold. Lausanne Sport is in the Swiss Super League, a competition with only 12 teams in the top flight. That structure can be a double edged sword. On one hand, a smaller league can be easier to climb if recruitment is smart and the academy is productive. On the other, a bad run can drop a club into a relegation scrap very quickly, and the financial hit of going down can be severe relative to the club’s scale.
The club’s recent league finishes tell a story. Fifth in 2023 to 2024 suggests a ceiling that is genuinely interesting. That is the kind of finish that can be sold as evidence of potential, especially if the club has infrastructure, a decent fan base, and a pathway to European qualification in a good year. But the regression to ninth and then bottom after 10 games suggests the floor is also uncomfortably low.
Sales documents calling the club an “established top flight contender” sit awkwardly next to the fact it has been relegated three times since 2014. That does not mean the club is unsellable. It means the pitch is likely to focus on the Swiss market’s stability, the possibility of talent trading, and the chance to professionalise operations. Buyers in 2026 are often less interested in matchday glamour and more interested in systems, data, and the ability to generate transfer value.
One more detail matters for context: Lausanne Sport plays Manchester United in a friendly earlier this month at Carrington. Friendlies like that can be read two ways. They can be a sign of a functioning network, with relationships and access. Or they can be a reminder that the smaller club exists in the shadow of the bigger one, which can be a tough sell to local supporters and a complicated reality for a new owner to manage.
Manchester United’s crisis mood and why it changes the calculus
It is impossible to separate this sale story from Manchester United’s current turbulence. United sits 16th after the Bournemouth defeat, and the reporting notes speculation about Michael Carrick’s future. The detail that he is the third boss in just over two and a half years under INEOS led football operations is damning, because it implies the decision making structure is still searching for a settled identity.
When a club as large as United is underperforming, everything else becomes secondary. That is not just about money, although money is obviously part of it. It is also about bandwidth. The same executives, advisers, and football operations staff who might oversee a multi club model are suddenly pulled into crisis meetings, recruitment overhauls, communications planning, and the endless churn of a high pressure environment.
There is also a narrative risk for Ratcliffe personally. He arrives as the “football side” of the ownership, the one expected to improve sporting performance. If results do not improve, critics will question priorities, governance, and whether INEOS is spread too thin. Selling Lausanne Sport, and potentially Nice, allows INEOS to say, in effect, “we are focusing”. Fair enough, it is a defensible stance, even if it is also an admission that the broader sports empire is being trimmed.
None of this proves the sale is directly funding Manchester United activity. The source material does not say that. But in football, perception matters. A sale will be read by many supporters as an attempt to concentrate resources and attention on United, especially given the quote about reducing capex and spending every pound carefully.
What’s Next
The immediate next step is the market test. With Alvarez & Marsal reportedly circulating the Project Striker prospectus, the key question becomes: who bites, and at what price? The source material does not name potential bidders, so any guesswork would be just that. But the profile of likely buyers in 2026 is fairly clear across European football: private investors looking for a platform club, multi club groups seeking another node in their network, or regionally connected money that values presence in Switzerland for business as much as for sport.
What should observers watch for? First, whether INEOS insists on a clean exit or whether it keeps a minority stake. A retained stake can preserve relationships, and it can soften the optics of walking away. But it also keeps complexity on the books, which is exactly what a “focus on United” strategy would try to avoid. Second, watch the messaging around Lausanne Sport’s sporting plan during the sale process. Clubs in relegation trouble can become unstable when staff and players sense uncertainty. A buyer will want reassurance that the club is not drifting while the paperwork moves around.
Longer term, the sale could be a marker for a broader shift in how INEOS approaches sport. The source material notes INEOS has previously sponsored the New Zealand national rugby union team, an America’s Cup team led by Sir Ben Ainslie, and Tottenham Hotspur, and that those deals have ended in recent years. If Lausanne Sport and Nice both move on, INEOS looks less like a sprawling sports investor and more like a group placing a single, very large bet on Manchester United. That is high risk, high visibility, and it will be judged almost entirely on results at Old Trafford.
Closing thoughts, a strategic retreat or a necessary reset?
The sir jim ratcliffe lausanne sport sale, as reported, reads like a pragmatic decision rather than a dramatic one. Lausanne Sport has struggled on the pitch, INEOS is publicly emphasising cost control in 2026, and Manchester United is in a position where focus is not a luxury, it is a necessity. Put those together and a sale starts to look less like a surprise and more like the logical next move.
But it also raises an uncomfortable point about the multi club dream. It is often sold as modern football’s answer to inefficiency, a network that can out recruit and out develop rivals. Yet when the flagship club is in turmoil, the network can quickly feel like clutter. Lausanne Sport’s sale process, with advisers engaged and prospectuses circulating, suggests INEOS is choosing simplicity over sprawl.
Whether that works depends on what happens next at Manchester United, because that is where the spotlight is. If United stabilises and improves, this will be framed as smart prioritisation. If it does not, critics will say INEOS sold the side projects and still could not fix the main one. And that, in football, is the only verdict that really sticks.